
81,000 HMRC Letters: Crypto tax has entered a new phase
If you thought crypto tax was something HMRC wasn’t paying much attention to, recent events are suggesting otherwise.
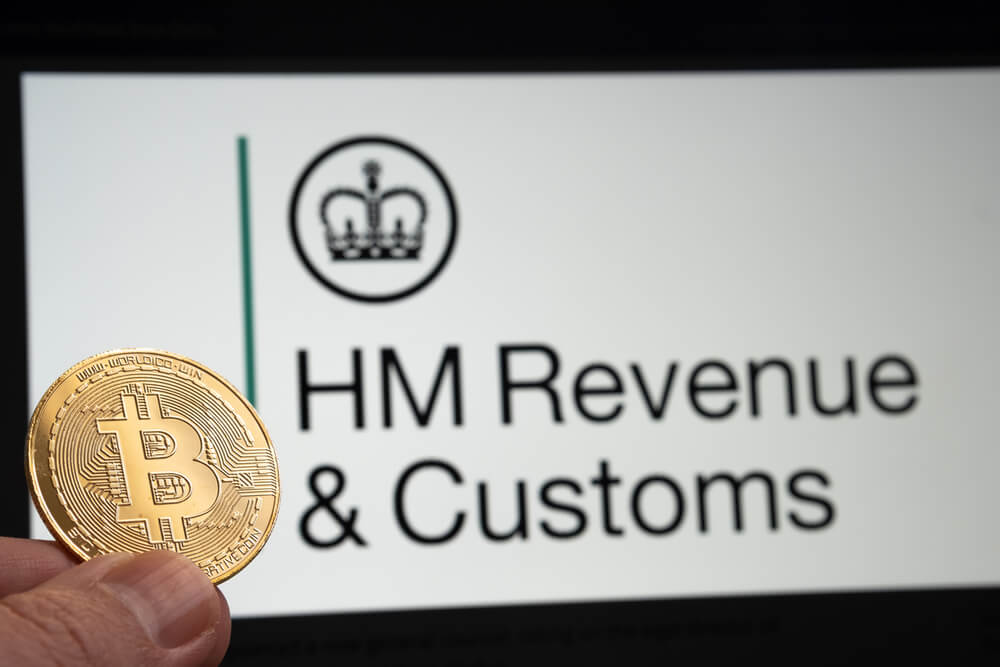
As reported recently by the BBC, HMRC sent 81,000 warning letters to people they believe have crypto-related tax obligations. Their message is clear: crypto tax compliance is becoming an increasing priority.
At the same time, new reporting rules and enhanced data-sharing arrangements mean HMRC now has access to more information about crypto transactions than previously.
Whether you hold cryptocurrency as an investment, trade regularly, earn staking rewards or use multiple wallets and exchanges, it’s really important to understand what these changes could mean for you.
Why Is HMRC Focusing on Crypto?
The crypto market has matured significantly over the past few years, along with HMRC’s approach to taxation.
Many crypto investors presume that their activity is difficult for tax authorities to track, especially if assets are held across multiple exchanges, wallets or platforms. However, recent developments mean that assumption is becoming increasingly risky.
Three key changes are driving this change:
- The introduction of CARF (Crypto-Asset Reporting Framework)
- HMRC’s Guidelines for Compliance 13 (GfC13)
- HMRC research highlighting the challenges taxpayers face when reporting crypto correctly
Taken together, these developments signal a new era of crypto tax compliance.
CARF means more Crypto Data is being shared
The Crypto-Asset Reporting Framework (CARF) came into force in the UK on 1 January 2026.
Under these rules, many crypto service providers are now required to collect and report information about their users. The UK will also receive information from participating overseas jurisdictions, giving HMRC greater visibility of crypto activity that takes place even outside the UK.
For crypto investors, this means transactions are becoming far more transparent.
If you’ve ever bought, sold, swapped, transferred or earned crypto across multiple platforms, HMRC may have access to more information about your activity than you realise.
That doesn’t mean you’ve done anything wrong. It does mean however that keeping accurate records and reporting transactions correctly has become more important than ever.
Crypto Tax isn’t always straightforward
One of the biggest challenges for crypto investors is that taxable events sometimes aren’t obvious.
Selling cryptocurrency for cash is often recognised as taxable, but tax implications can also arise when:
- Swapping one cryptocurrency for another
- Receiving staking rewards
- Earning crypto income
- Spending cryptocurrency on goods or services
- Participating in certain DeFi activities
For investors using multiple wallets and exchanges, transaction histories can quickly become fragmented and hard to track.
As a result, it is not uncommon for people to accidentally miss transactions or misunderstand their tax position.
HMRC wants more than just a number
HMRC’s Guidelines for Compliance 13 place a strong emphasis on ensuring tax returns are accurate, complete and supported by evidence.
It’s no longer enough to guess your crypto position or rely on incomplete information.
The key question is not simply:
“What is my crypto gain?”
It’s:
“Can I show how that figure was calculated?”
If HMRC asked you questions about your return, you should be able to demonstrate where the numbers came from, how transactions were identified and how your gains, losses and income were calculated.
Why HMRC’s research matters
In May 2026, HMRC published research highlighting that many crypto investors struggle to understand their tax obligations.
Importantly, the research recognised that compliance issues are not always caused by deliberate non-disclosure. In a lot of cases, investors simply find crypto tax rules confusing or have difficulty bringing together records from multiple platforms.
This is also the reality faced by many crypto holders.
As crypto portfolios become more complex, calculating an accurate tax position manually becomes increasingly challenging.
The standard is changing
The recent warning letters, combined with CARF and HMRC’s evolving compliance approach, suggest that expectations are changing.
Historically, some investors may have focused on producing a reasonable estimate of their crypto gains.
Today, the expectation is increasingly that taxpayers can provide a complete and well-supported calculation based on their full transaction history.
The question is shifting from:
“What’s my crypto tax bill?”
to:
“Can I evidence exactly how it was calculated?”
Don’t wait until HMRC contacts you
Receiving an HMRC letter doesn’t necessarily mean you’ve done something wrong. It can however be a sign that your crypto activity has been identified and may require a review.
The best approach is to get ahead of the process.
Reviewing your crypto position now, ensuring your records are complete and addressing any gaps before HMRC raises questions can help reduce stress and avoid potential complications later.
Crypto may be digital, but the tax obligations are very real.
How SG Accounting and Recap can help
If you’re unsure about your crypto tax position, professional support is available.
SG Accounting works alongside crypto tax specialists Recap to help investors understand their obligations, accurately calculate their gains and income, and ensure their tax returns are supported by complete transaction data.
Whether you’ve made a handful of trades or manage a complex portfolio across multiple exchanges and wallets, our specialist team can help simplify the process and provide clarity on your reporting obligations.
As an SG Accounting client, you’ll also receive an exclusive 20% discount on Recap crypto tax software.
Need help with crypto tax? Get in touch with our specialist tax team today to discuss your situation and stay ahead of the changing compliance landscape.
Note: All the information and advice in this blog post was correct at the time of writing.

Share This Article, Choose Your Platform!
Related Posts
Have a question? Get in touch.
Our team of contractor accounting specialists is here to help.